Sentiment Analysis For Financial Markets
This project created by Jing Wen, Qichen Liu, and Erkan Tas argues that the language financial media use and how they write can signal short-term stock price movements. The project uses Natural language processing and deep-learning techniques to process the positive or negative language into a measurable sentiment statistic and then turn that sentiment into a stock return prediction.
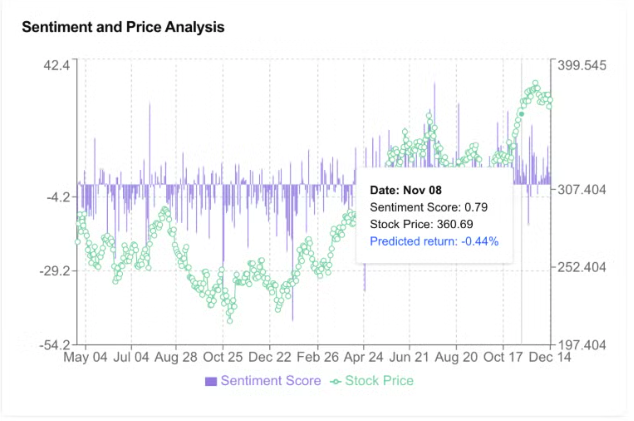
The graph above shows the sentiment score (purple) and the actual stock price (green). In this instance, it analyzes Microsoft. The purple bars here are the quantified tone of the news on any given day regarding Microsoft. The part of the graph most interesting is towards the right, where Microsoft stock prices move from 300 range to the 350-400 range. In this specific time frame you can see the sentiment score stays positive and the stock prices reflect this by rising consistently. This demonstrates an association between the two pieces of data.
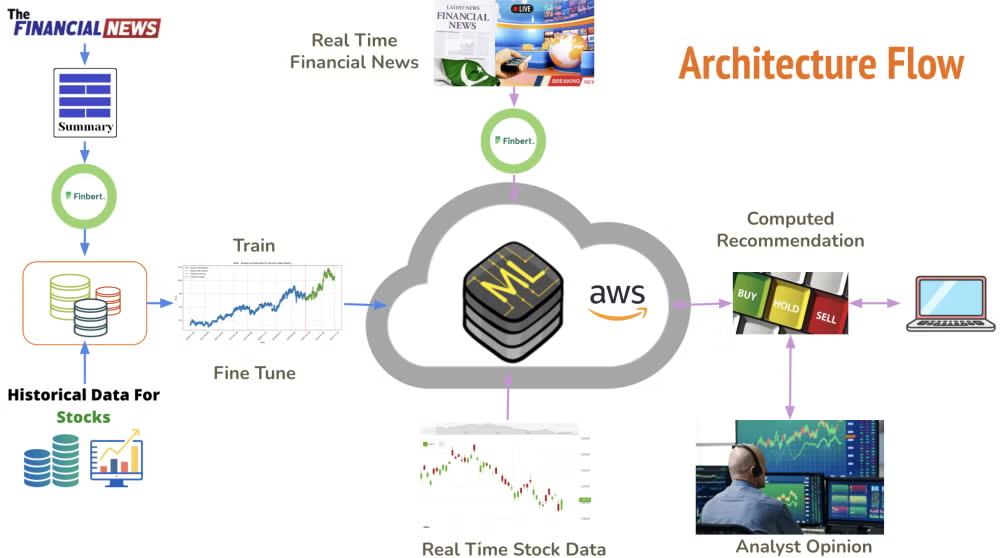
The creation of the data set model used concise summaries of past news articles and media sentiment combined with historical stock data changes to train the model and then use it with real-time financial news and real-time stock price data to compute and analyze the data it was given.